November 16, 2026
SBA 504 Loans for Georgia Restaurant Owners


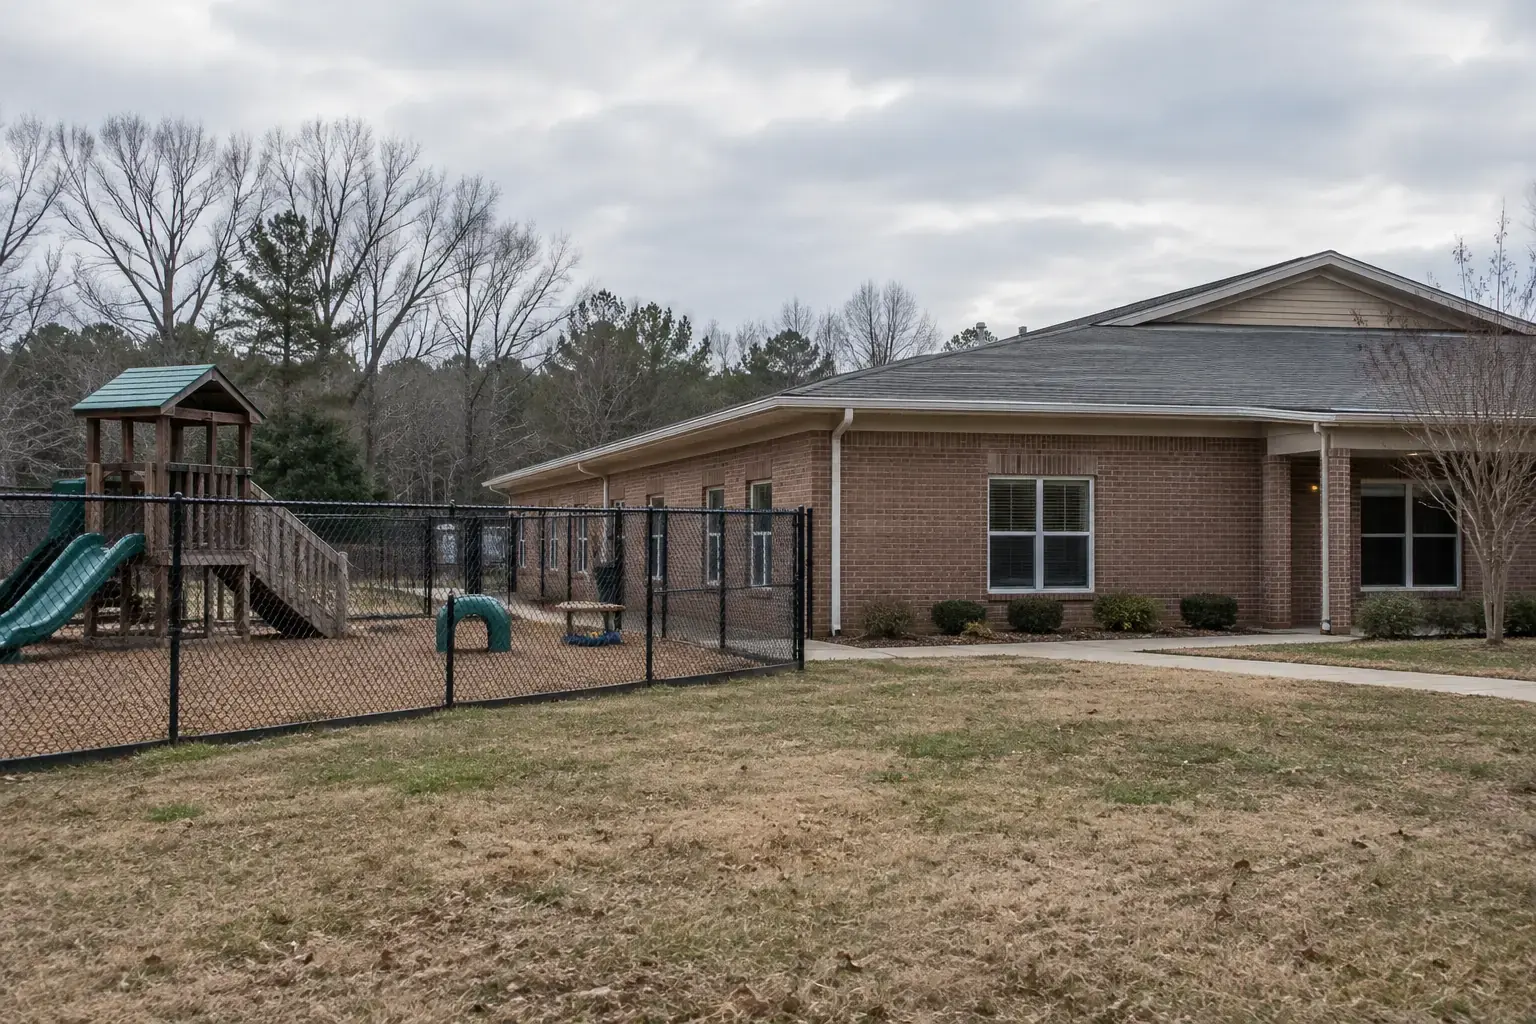
Owning the building your child care center operates from can change your costs and your long-term stability. SBA 504 loans for Georgia child care center owners are designed for exactly that: buying a building, building a new center, or renovating and expanding one you own. This guide explains how the loan is typically structured, what you may need to put down, what the loan can and cannot pay for, and what to sort out before you talk to a lender.
Yes, in most cases. An SBA 504 loan can finance the purchase of an existing building, the construction of a new one, or major renovations, as long as your child care business will own and occupy the property and the project meets the program's rules. It cannot be used for working capital or inventory, and it cannot be used for speculative real estate.
That makes it a good fit if you currently lease your space and want to stop paying rent to a landlord, or if you want to open a second location in a building you control. Georgia Small Business Capital (GSBC) is a private, non-profit CDC that has administered the SBA 504 Loan Program since 1989, and our team has over 35 years of experience helping Georgia business owners with these projects. You can also read about our approach on our page for SBA 504 loans for Georgia child care centers.
A 504 project has three pieces. A bank or credit union provides the first loan and holds the first lien, which means it gets repaid first if the loan ever goes into default. A CDC provides a second loan, funded through an SBA-backed debenture. A debenture is simply a long-term bond the CDC sells to fund its share of your project. You provide the remaining cash, called your borrower contribution, which is the 504 version of a down payment.
Under the federal rules, your contribution must be at least 10 percent of project costs, the CDC share can be up to 40 percent, and the first-lien lender provides the balance. In a typical deal that puts the bank or credit union at about 50 percent.
Here is a hypothetical example. A child care operator buys a building for $1,800,000. The table shows a typical split with a 10 percent contribution, and how it could change if the lender asks for 15 percent.
Piece of the projectTypical 10% contributionIf 15% is requiredBank or credit union (first lien, about 50%)$900,000$900,000CDC / SBA 504 portion$720,000 (40%)$630,000 (35%)Borrower contribution$180,000 (10%)$270,000 (15%)Total project$1,800,000$1,800,000
This is an illustration only. Actual amounts depend on the property, the appraisal, the first-lien lender, and your business. Closing costs and fees are separate and vary by deal.
At least 10 percent of project costs is the federal floor, and that is the number most owners hear about first. Your actual contribution can be higher.
One reason is the type of building. Child care centers are often built or modified for a single use, with classroom layouts, specialized restrooms, and secured play areas. When a building is limited to one purpose, lenders may treat it as a limited or single purpose property, which can mean a larger contribution. Whether a particular building is treated that way is a lender and CDC decision, so it is worth raising the question at the start instead of after you have a purchase contract.
The strength of your business, the location, and the structure of the deal can also play a role. A CDC can walk you through the numbers for your specific project.
The 504 program is built around fixed assets. For a child care center, the eligible uses typically include:
What it does not cover is just as important. Payroll, tuition shortfalls, curriculum, supplies, and other operating expenses are working capital, which is not an eligible use of a 504 loan. If you need both a building and working capital, talk with a lender about how to structure the two needs separately.
The 504 program is for businesses that use the property, not for investors. For an existing building, your business generally must permanently occupy and use at least 51 percent of the rentable space. For new construction, the requirement is generally at least 60 percent.
For most child care operators this is easy to meet, since the center fills the building. If you are looking at a larger property and hope to lease out part of it, the leasing limits matter. Our guide on the SBA 504 loan program explains the basics, and your CDC can confirm the numbers for a specific building.
An SBA 504 loan for a child care center is long-term, fixed-rate financing for owning the building your center operates from. A bank or credit union typically funds about 50 percent, a CDC funds up to 40 percent through an SBA-backed debenture, and you contribute at least 10 percent, sometimes more. It covers real estate and long-term equipment, not day-to-day operating costs, and your business must occupy most of the property.
For a closer look at how a project typically moves from first call to closing, see our proven process.
Each deal is reviewed individually, but there are some general points. The business must operate for profit, be owner-occupied as described above, and meet the SBA's size standards, which the program often measures by tangible net worth and average net income. SBA financing is also generally limited to businesses whose direct and indirect owners are U.S. citizens, U.S. nationals, or lawful permanent residents. Your CDC can review the current rules with you, since SBA program requirements can change.
Leasing keeps your upfront cash lower, but you are exposed to rent increases and lease renewals, and you may be investing in improvements in a building you do not control. Owning, on the other hand, builds equity and gives you control of the space your families rely on. Ownership also brings real responsibilities, including maintenance, property taxes, and insurance. If you are weighing the decision, run the numbers for your own situation and consider speaking with a CPA or attorney about the tax and legal side.
If you already own the property your center operates from, the SBA 504 Refinance Program may be worth a look. The rules for what debt qualifies are specific, so read about SBA 504 refinancing or ask us whether your loan might fit.
For child care center owners in Georgia, an SBA 504 loan can turn a monthly rent payment into building ownership with long-term, fixed-rate financing. The keys are to plan the project before you sign anything, ask early how your building will be treated, and confirm licensing and zoning. If you would like to talk through your options, the GSBC team is happy to help Georgia child care owners understand what a project could look like. Call us at 404-373-8601.
Yes, in most cases. A 504 loan can finance new construction as well as the land, as long as your business will own and occupy the center. For new construction, the owner-occupancy requirement is generally at least 60 percent of the building.
The federal minimum is at least 10 percent of project costs. It can be higher depending on the property, such as a building limited to one purpose, and the details of your deal. A CDC can estimate the number for your project.
No. A 504 loan is for fixed assets like real estate and long-term equipment. Working capital, including payroll and supplies, is not an eligible use.
Sometimes. Your business generally must occupy at least 51 percent of an existing building or at least 60 percent of a new one, which limits how much you can lease out. Check the details with your CDC before you buy.
SBA financing is generally limited to businesses whose direct and indirect owners are U.S. citizens, U.S. nationals, or lawful permanent residents. Rules can change, so confirm the current requirements with your CDC.